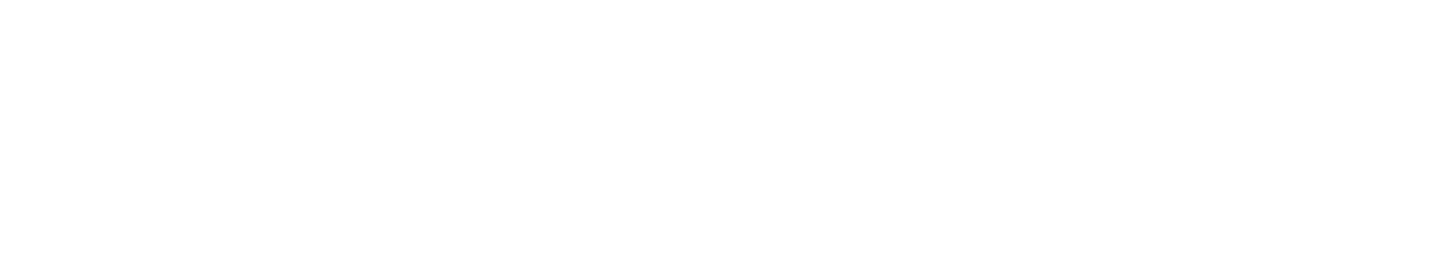
The second derivative of an option’s price with respect to the price of an underlying:
Back to glossary index